Buying on Lake Hickory and wondering how financing works for waterfront homes? You are not alone. Lake properties come with extra checks that can slow you down if you are not ready. In this guide, you will learn what lenders look for, how Hickory’s lake rules affect loans, and the exact steps to prepare a clean, fast file. Let’s dive in.
Why lake homes are different
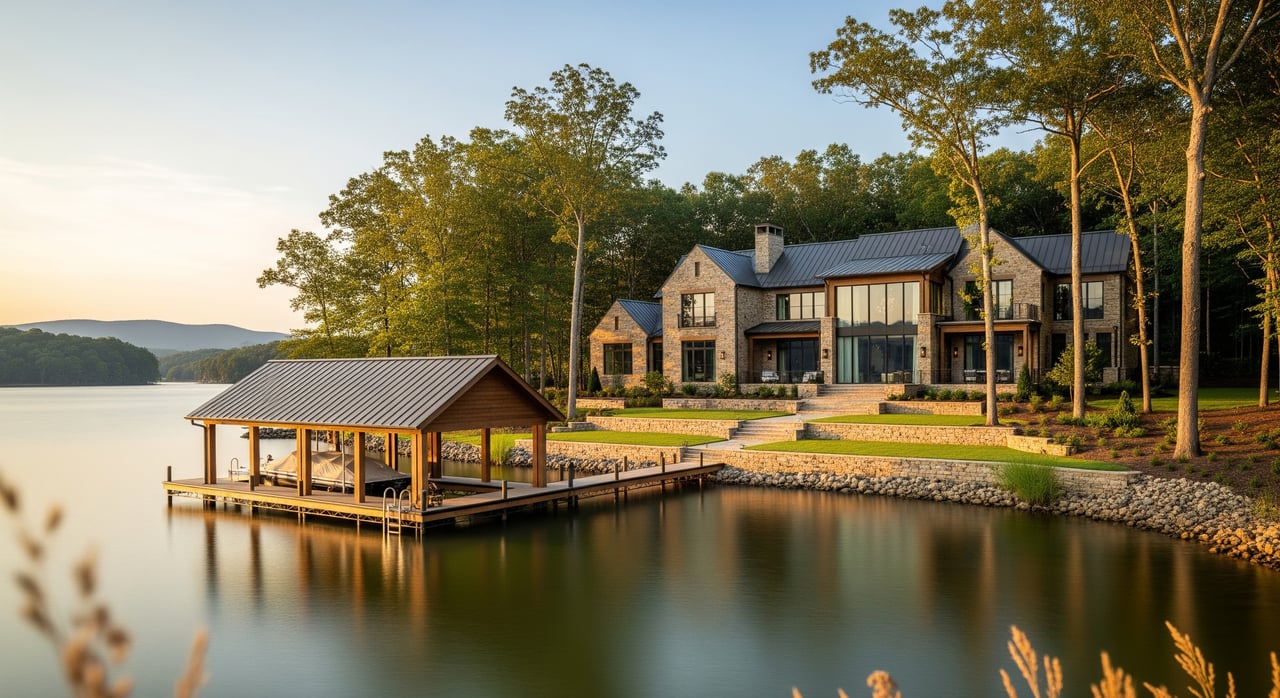
Lake Hickory is a Duke Energy managed reservoir, which means docks, piers, and shoreline work often require permits. Duke’s Lake Services explains what is allowed and what documentation you need for shoreline activities. Review the permit process on the Duke Energy Lake Services page.
Hickory’s overall prices sit below larger metros, but lakefront listings trade at a premium for features like direct access, a private dock, long views, and water depth. Reported medians for 2024–2025 in Hickory generally run from the mid to high $200s into the low $300s depending on the month and dataset, and waterfront homes often price higher than inland comparables. You can scan local trends on Zillow’s Hickory market snapshot.
What lenders check about you
Credit, DTI, income, and reserves
Lenders focus on your payment capacity and stability. Automated underwriting for conventional loans can allow a total debt-to-income ratio near 50 percent with the right compensating factors, but every file is different. See Fannie Mae’s overview of debt-to-income ratios for context. Expect verification of income, employment history, assets for down payment, and sometimes cash reserves after closing.
Choose the right loan program
- Conventional conforming: Strong borrowers often get the best pricing here. Be mindful of loan limits. The 2025 one-unit baseline is 806,500 dollars. If your lake purchase exceeds the local limit, you may need a jumbo loan with stricter requirements.
- FHA: More flexible credit and down payment options, but the home must meet HUD minimum property standards and the FHA appraisal will flag health and safety issues. Review common FHA property and appraisal guidelines.
- VA and USDA: These can be excellent options for eligible borrowers. Lender overlays still apply, and property features must fit program rules.
What lenders check about the property
Appraisal for waterfront value
Appraisers must analyze site, utilities, and special amenities. On the lake, comparable sales can be limited, and adjustments for docks, views, and water depth must be market supported. See Fannie Mae’s guidance on the site section of the appraisal. A scarce comp set can raise the risk of a low appraisal, so plan ahead.
Title, survey, and shoreline rights
Your lender will require a lender’s title insurance policy. A current survey should show boundaries, easements, and any dock or shoreline encroachments. Learn why lenders require title insurance from the Consumer Financial Protection Bureau. On Lake Hickory, verify that any dock or shoreline structure is properly permitted with Duke Energy or documented as grandfathered.
Flood zones and insurance
If any insured structure sits in a FEMA Special Flood Hazard Area, flood insurance is typically mandatory for federally related loans. Check the property on FEMA’s Flood Map Service Center. If it is in a high-risk zone, you may need an Elevation Certificate to quote premiums.
Septic, wells, and health approvals
Many lake homes use private wells and septic. Lenders often ask for permits and recent inspections or tests. Catawba County Environmental Health issues and maintains septic and well permits, which you can confirm with the county’s septic and wells resources.
HOA or condo project review
If the property is in an HOA, PUD, or condo, the association’s financials, insurance, reserves, and litigation status are reviewed. Properties in projects that fail eligibility tests may not qualify for financing. See Fannie Mae’s project standards overview.
Cost factors that change approval
Waterfront proximity can raise homeowners and flood insurance costs. Lenders include taxes and insurance in your qualifying payment, so higher premiums can push your DTI and reduce borrowing power. Shop insurance early and share quotes with your lender to keep your approval on track.
Your Lake Hickory financing checklist
Use this list to avoid closing surprises:
Get prequalified with lake experience
- Share that you are shopping on Lake Hickory and whether you need a dock or deep-water lot.
- Ask your lender to compare conventional, FHA, VA, and USDA scenarios with realistic insurance estimates.
Gather borrower documents
- Photo ID, recent pay stubs, W-2s or tax returns for two years if self-employed, bank statements, and gift letters if applicable.
Verify property details early
- Request seller copies of Duke Energy dock or shoreline permits and any HOA covenants and insurance certificates.
- Order a current survey showing the dock location, easements, and encroachments.
Run key property checks
- Pull the FEMA flood map and ask whether an Elevation Certificate is available if the home is near the water’s edge.
- Collect Catawba County septic and well permits, plus recent maintenance or test results.
Order inspections the lender may require
- General home inspection, septic inspection and pump report if needed, and well water testing.
Prepare for appraisal outcomes
- Work with your agent to assemble the best waterfront comps. If value comes in low, consider a price adjustment, a seller credit for repairs, more cash to close, or an appraisal review.
Write smart contingencies
- Include time for septic and well testing, flood determination, HOA review, and shoreline permit verification.
Avoid common Hickory surprises
- Jumbo threshold: If your price is above the conforming limit, expect tighter credit, more reserves, and a larger down payment.
- Unpermitted shoreline work: Missing or outdated dock permits can delay underwriting. Get documentation up front.
- Sparse comparables: Waterfront homes are unique. Set expectations on value and timing before you order the appraisal.
Ready to get started?
When you prepare for both the borrower checks and the lake-specific property checks, your financing gets smoother and your negotiation power goes up. If you want a clear plan and lake-smart support from search to closing, connect with Kathryn Herman & Carly Pruitt for local guidance and a closing-ready strategy.
FAQs
What credit and DTI do lenders expect for Lake Hickory homes?
- Conventional approvals often hinge on strong credit and a total DTI near or below 50 percent depending on your overall file, while government programs can be more flexible but still require full documentation.
Do I need flood insurance for a Lake Hickory house?
- If any insured structure is in a FEMA Special Flood Hazard Area, lenders typically require flood insurance, and they may require it even outside high-risk zones.
Will an unpermitted dock stop my loan in Hickory?
- It can delay or block closing if the underwriter cannot confirm the dock is permitted, grandfathered, or removable, so collect Duke Energy permit records early.
How are appraisals different for waterfront properties?
- Appraisers must quantify the value of features like a private dock, view, and water depth using market-supported comps, which can be scarce on the lake and may lead to conservative valuations.
Can I use FHA or VA for a Lake Hickory purchase?
- Often yes, if you and the property meet program rules, including minimum property standards and water or septic requirements that can be more stringent than conventional.
What septic or well paperwork will my lender want?
- Expect to provide county permits and recent inspections or tests for any private well and septic system, plus repair receipts if issues were found.